

605 withholding code: 5/10 VAT withholding on event services
In short
The 605 withholding code is the e-invoice code for 5/10 VAT withholding on organization (event) services in Turkey. Here is what it covers, who declares the VAT, how the invoice shows it and which customers it never applies to, with sources.
Key points
- 605 is the withholding code for organization (event) services at a 5/10 rate; 604, catering service, carries the same rate.
- For organization services the withholding applies only to the designated buyers listed in the VAT General Implementation Communiqué, not to every customer.
- The buyer declares the withheld VAT on VAT Return No. 2; the seller declares the rest on VAT Return No. 1.
- If the VAT-inclusive amount does not exceed the invoicing threshold, no withholding is made; above it, withholding covers the whole amount and the price cannot be split.
Contents
The 605 withholding code is the e-invoice code for the 5/10 VAT withholding on organization (event) services in Turkey [1]. It applies only to the designated buyers named in the VAT General Implementation Communiqué (Katma Değer Vergisi Genel Uygulama Tebliği, "the Communiqué") [2].
Withholding codes raise a lot of questions. This article rests on the consolidated text of the Communiqué that the Turkish Revenue Administration (GİB) published in 2026 [3].
What does the 605 withholding code cover?
The 605 withholding code stands for organization services in GİB's code list, at a rate of 5/10 [1]. Code 604, catering service, carries the same rate [1]. The Communiqué treats the two in one section: when catering and organization services go to designated buyers, those buyers withhold VAT at 5/10 [2]. GİB's rate table agrees [4].
The scope is broad: concerts, fairs, celebrations, parties, cocktails, receptions, congresses, seminars, panels, promotions and similar services [2]. What the organizer buys from the venue, such as a hall or hotel, is outside the withholding [2].
In the Communiqué's own example, an organization firm arranges a public body's celebration and agrees a hotel deal for the guests. The hotel's accommodation and hall services are not subject to withholding; the VAT calculated on the total the firm invoices to the public body is withheld at 5/10 [3].
Who declares the VAT under partial withholding?
Under partial withholding, the buyer declares and pays its share of the calculated VAT as the responsible party, at the withholding rate; the seller declares the rest [2]. At 5/10, half of the VAT sits with the buyer and half with you [1][2].
The buyer declares the withheld tax on VAT Return No. 2 [2]. You enter the amount excluding VAT, the VAT rate and the buyer's withholding rate in the "Partial Withholding Transactions" table of VAT Return No. 1 [5]. If you do not want a refund because of the withholding, you leave the refund table blank [5].
How is an invoice with code 605 issued?
On an e-invoice the withholding code sits under the "WithholdingTaxTotal" element, and 605 is picked from that list [1]. The invoice shows the transaction amount, the VAT calculated, the withholding rate and the VAT the buyer withholds, on separate lines [3]. For the seller, this invoice is the document that proves withholding was applied to the calculated VAT [3].
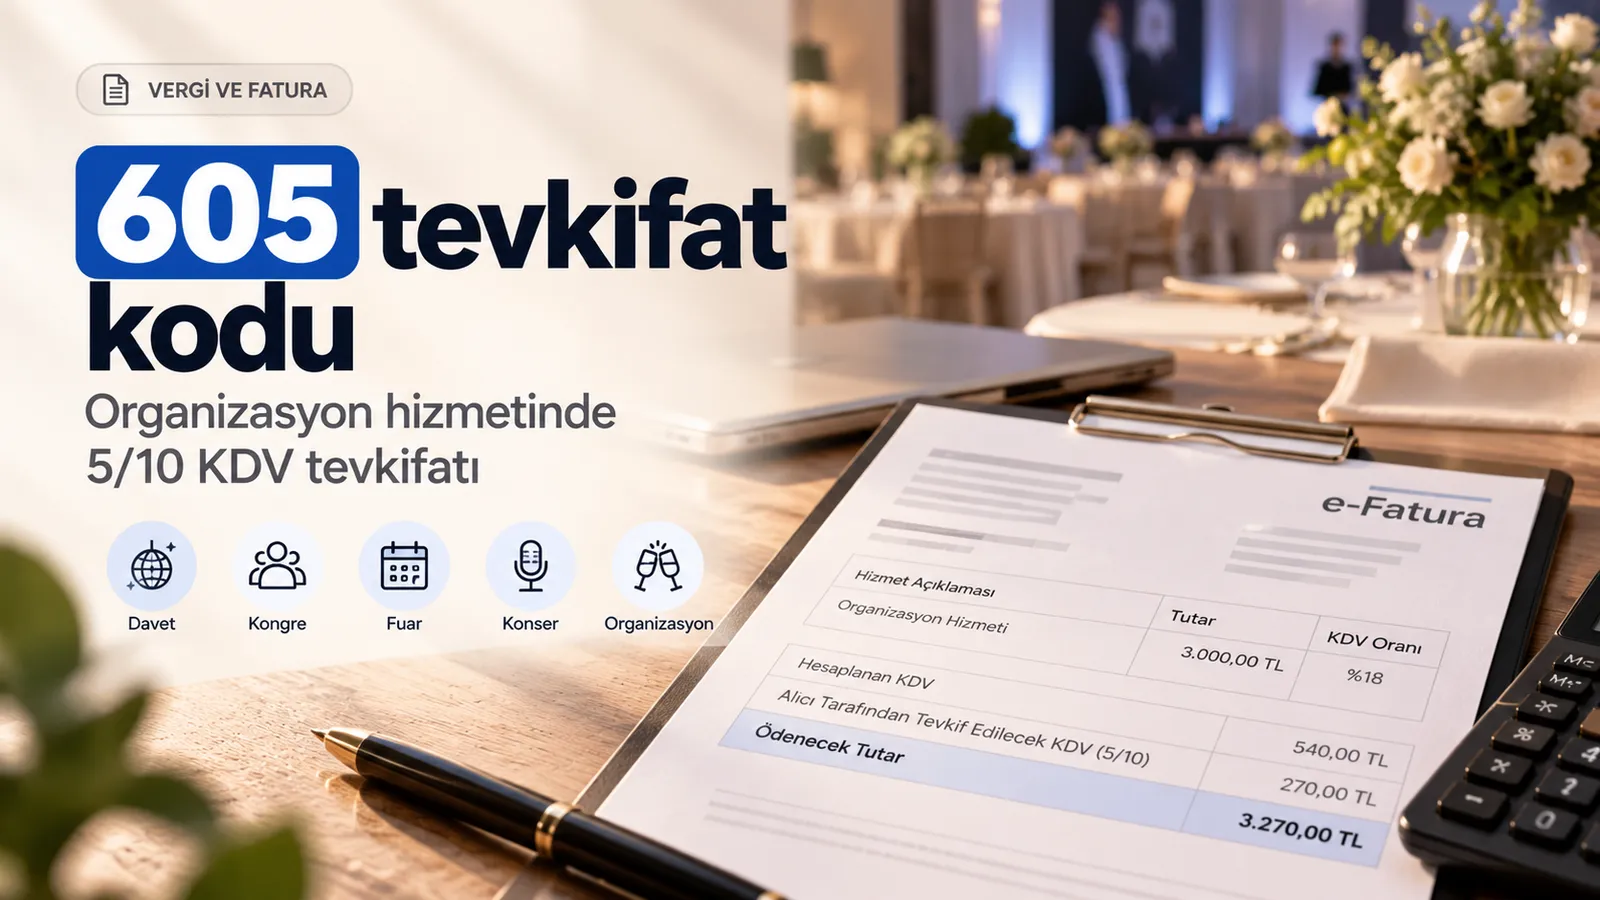
The Communiqué's official example takes a transaction of 3,000 TL excluding VAT, subject to 5/10 withholding [3]:
- Transaction amount: 3,000 TL
- VAT calculated: 540 TL
- Withholding rate: 5/10
- VAT withheld by the buyer: 270 TL
- Total including withholding: 3,540 TL
- Total excluding withholding: 3,270 TL
The amount left after withholding is written on the invoice in figures and in words [3]. The example uses an 18 per cent VAT rate [3]; use the rate your own transaction is subject to.
If you carry out a transaction subject to withholding together with one outside it, you may put both on a single invoice. The amount subject to withholding, the VAT on it and the VAT withheld are still shown separately [3].
Does withholding apply to every customer?
No. Withholding on organization services applies only to buyers on the Communiqué's list of designated buyers, which includes the administrations, institutions and bodies in the schedules attached to Law No. 5018, banks and companies whose shares trade on Borsa Istanbul [2]. If your customer is not on the list, this withholding does not apply [2].
As a rule, designated buyers do not withhold on services they supply to each other [2].
There is one more limit. If the VAT-inclusive amount of a transaction does not exceed the invoicing threshold set for the year under Article 232 of the Tax Procedure Law, no withholding is made; above it, withholding covers the whole amount [3]. You cannot split the price to avoid it [3]. I have left out this year's threshold because I could not confirm it from an official source.
Check first whether the buyer is a designated buyer. If not, the code and the withholding drop out.
Before you issue the invoice, check with your accountant that the transaction falls under the Communiqué. Our guide to calculating and declaring VAT (in Turkish) covers the VAT basics, and the e-invoice and e-archive page (in Turkish) shows how documents are issued electronically.
Frequently asked questions
What does the 605 withholding code stand for?
Organization services, at a withholding rate of 5/10.
Is the 605 withholding code used on every customer's invoice?
No. For organization services, withholding applies only to the designated buyers listed in the Communiqué.
Which amounts must a withholding invoice show separately?
The transaction amount, the VAT calculated, the withholding rate, the VAT the buyer withholds and the totals including and excluding withholding, on separate lines.
Related service
Invoices & orders
Purchase and sales invoices with order tracking.
Sources
- ebelge.gib.gov.tr (opens in a new tab)
- Katma Değer Vergisi Genel Uygulama Tebliği (I/C-2.1.3.1 ve 2.1.3.2.4) (opens in a new tab)
- KDV Genel Uygulama Tebliği, 2026 birleştirilmiş metin (GİB) (opens in a new tab)
- cdn.gib.gov.tr (opens in a new tab)
- KDV Genel Uygulama Tebliği, satıcıların beyanı (I/C-2.1.3.4.3.2) (opens in a new tab)
Related articles
Turkish VAT return penalty in 2026: deadline, amounts and voluntary disclosure
The Turkish VAT return penalty for 2026 is a first-degree irregularity fine of 2,600 TL to 35,000 TL, depending on the type of business. If the tax is also…
Collecting unpaid customer debts: from formal notice to enforcement
Collecting unpaid customer debts (veresiye, sales on credit) in Turkey starts with a formal notice and moves to enforcement. Limitation periods, how far a…