

Turkish VAT return penalty in 2026: deadline, amounts and voluntary disclosure
In short
The Turkish VAT return penalty for 2026 is a first-degree irregularity fine of 2,600 TL to 35,000 TL, depending on the type of business. If the tax is also paid late, a tax loss penalty or a voluntary disclosure surcharge comes on top. Here is the deadline, the amounts and the cheapest way out, based on official sources.
Key points
- Monthly and quarterly VAT returns are due by 23:59 on the 28th of the month after the period, and the tax is paid within the same window; the No. 2 return filed as a withholding agent is due on the 25th.
- Missing the deadline is a first-degree irregularity; the 2026 fine is 8,700 TL for a second-class merchant and 35,000 TL for a limited or joint-stock company.
- Under voluntary disclosure no tax loss penalty is charged, but the tax must be paid within 15 days with a 3.7% surcharge for each month or part of a month.
- If you file late before the tax office starts an audit, the tax loss penalty is halved.
Contents
- When is the VAT return due?
- How much is the VAT return penalty in 2026?
- What happens if the VAT is paid late?
- How does voluntary disclosure reduce the penalty?
- Example: a shop files its March return 10 days late
- Filed 10 days late under voluntary disclosure
- Filed late without meeting the disclosure conditions
- Never filed, tax office assesses it
The Turkish VAT return penalty for 2026 is a first-degree irregularity fine: 8,700 TL for a second-class merchant, 17,000 TL for a first-class merchant and 35,000 TL for a company [1][2]. Pay the VAT late as well and you face either a tax loss penalty or a voluntary disclosure surcharge [2].
Which one you get depends on who notices first. Act before the tax office does and the bill stays small. Below are the deadline, the 2026 amounts and a worked example for a small shop.
When is the VAT return due?
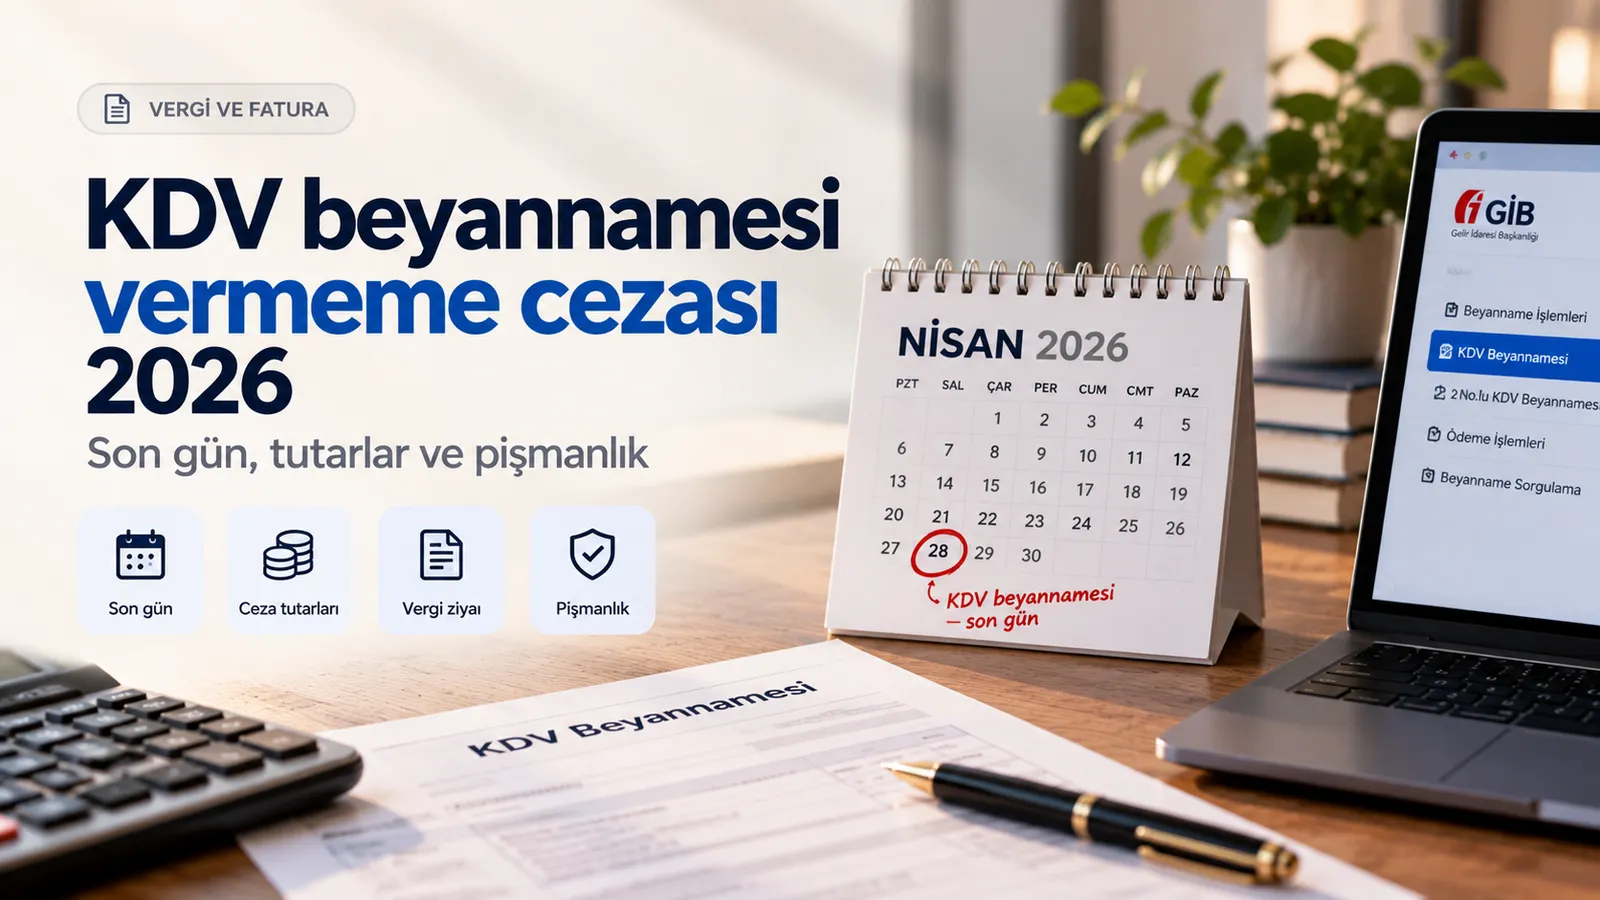
A monthly VAT return in Turkey is due by 23:59 on the 28th of the month after the tax period, and the tax is paid within the same window [3]. Quarterly filers have the same deadline, the 28th of the month after the quarter [3].
The Turkish Revenue Administration (GİB) moved the date to the 28th in December 2022, and it stays there until a new decision is made [4]. One exception: the No. 2 VAT return you file "as a withholding agent", when you withhold part of a supplier's VAT, is due on the 25th, and the tax is paid by the 25th as well [3][5].
If you receive invoices with VAT withholding, you are tracking two dates a month.
How much is the VAT return penalty in 2026?
The VAT return penalty for a missed deadline is a first-degree irregularity fine under Turkey's Tax Procedure Law (VUK) [2]. The fine depends on how your business keeps its books and is reset every year. The 2026 amounts were set by VUK General Communiqué No. 588 [1]:
| Business type | 2026 first-degree irregularity fine |
|---|---|
| Limited and joint-stock companies | 35,000 TL |
| First-class merchants and self-employed professionals | 17,000 TL |
| Second-class merchants | 8,700 TL |
| Other income tax filers | 6,000 TL |
| Simplified-method taxpayers | 4,000 TL |
| Tradespeople exempt from income tax | 2,600 TL |
Source: [1]
If the return is never filed and the tax office has to assess the tax base itself, these amounts are doubled [2].
What happens if the VAT is paid late?
If the VAT is paid late, it leads either to a tax loss penalty or, under voluntary disclosure, to a surcharge at the late payment rate [2]. When tax is not assessed on time because the return was late, the law calls it tax loss, and the penalty equals the unpaid tax [2]. There is a discount: if you file late on your own, before an audit starts or the case goes to the assessment committee, the penalty is halved [2].
When one act causes both a tax loss and an irregularity, the two fines are not added; only the larger one is charged [2]. In a month with a large VAT bill, that will be the tax loss penalty.
The late payment surcharge has been 3.7% per month since 13 November 2025; the previous rate was 4.5% per month [6].
How does voluntary disclosure reduce the penalty?
Under voluntary disclosure, no tax loss penalty is charged [2]. You have to petition the tax office on your own and meet these conditions [2]:
- Nobody reported the same issue to the authorities before your petition.
- The petition is filed before a VAT audit starts or the case is sent to the assessment committee.
- A return that was never filed is submitted within fifteen days of the petition [2].
- The tax is paid within the same fifteen days, with a surcharge at the late payment rate for each month or part of a month [2].
"Part of a month" matters: even a few days late costs a full month of surcharge [2].
The provision itself only mentions the tax loss penalty [2]. Missing the filing deadline is listed separately as a first-degree irregularity [2]. Ask your accountant whether that fine still applies when you disclose voluntarily.
Example: a shop files its March return 10 days late
The figures below use the penalty table, the surcharge rate and the VUK rules above [1][2][6]. The amounts are illustrative.
Take a corner shop run as a second-class merchant. Its VAT payable for March 2026 is 20,000 TL. The deadline was 28 April, and the return was not filed.
Filed 10 days late under voluntary disclosure
No tax loss penalty. The delay is under a month, but a full month of surcharge applies: 20,000 TL × 3.7% = 740 TL. In the worst case, the 8,700 TL irregularity fine for the late return is added.
Filed late without meeting the disclosure conditions
The tax loss penalty is halved: half of 20,000 TL, so 10,000 TL. The 8,700 TL irregularity fine is lower, so only the 10,000 TL is charged.
Never filed, tax office assesses it
The full tax loss penalty applies: 20,000 TL. The doubled irregularity fine of 17,400 TL is lower, so again only the larger one is charged.
Even with the irregularity fine, voluntary disclosure is the cheapest route: its total is less than half of what the shop pays when the tax office finds the gap. I left out the surcharge or interest that also builds up in the second and third cases, so the real gap may be wider.
The VAT guide covers how VAT is calculated and reported (in Turkish).
Frequently asked questions
When is the Turkish VAT return due?
Monthly and quarterly VAT returns are due by 23:59 on the 28th of the following month, and the tax is paid in the same window. Returns filed as a withholding agent are due on the 25th.
How much is the fine for filing a VAT return late in 2026?
A first-degree irregularity fine: 35,000 TL for companies, 17,000 TL for first-class merchants and 8,700 TL for second-class merchants in 2026.
Does voluntary disclosure cancel every penalty?
No. It only removes the tax loss penalty, and you pay a surcharge at the late payment rate for each month or part of a month. Missing the filing deadline is listed as a separate irregularity in the law; ask your accountant whether that fine applies.
Related service
Invoices & orders
Purchase and sales invoices with order tracking.
Sources
- Vergi Cezaları (VUK ceza tutarları, 588 Sıra No'lu Tebliğ, 2026) (opens in a new tab)
- 213 sayılı Vergi Usul Kanunu (Madde 336, 341, 344, 352, 371) (opens in a new tab)
- Beyanname Verme ve Ödeme Süreleri (opens in a new tab)
- KDV Beyannamelerinin Verilme ve Ödeme Süreleri - VUK-149/2022-12 - Alomaliye.com (opens in a new tab)
- KDV 2 NOLU BEYANNAME VERME VE VERGİ ÖDEME SÜRESİ (opens in a new tab)
- Gecikme Zammı Oranları (opens in a new tab)
Related articles
605 withholding code: 5/10 VAT withholding on event services
The 605 withholding code is the e-invoice code for 5/10 VAT withholding on organization (event) services in Turkey. Here is what it covers, who declares the…
Collecting unpaid customer debts: from formal notice to enforcement
Collecting unpaid customer debts (veresiye, sales on credit) in Turkey starts with a formal notice and moves to enforcement. Limitation periods, how far a…